Free family credit manager

Your whole family's credit, in one place.

Credit Kindred puts your partner, your kids and your parents on one household board. Each adult joins by their own consent. Every score carries its bureau, model and date, and every person has a next step with a day on it.

FreeNo card offersWorks in any browser
Sample household5 people · 1 board
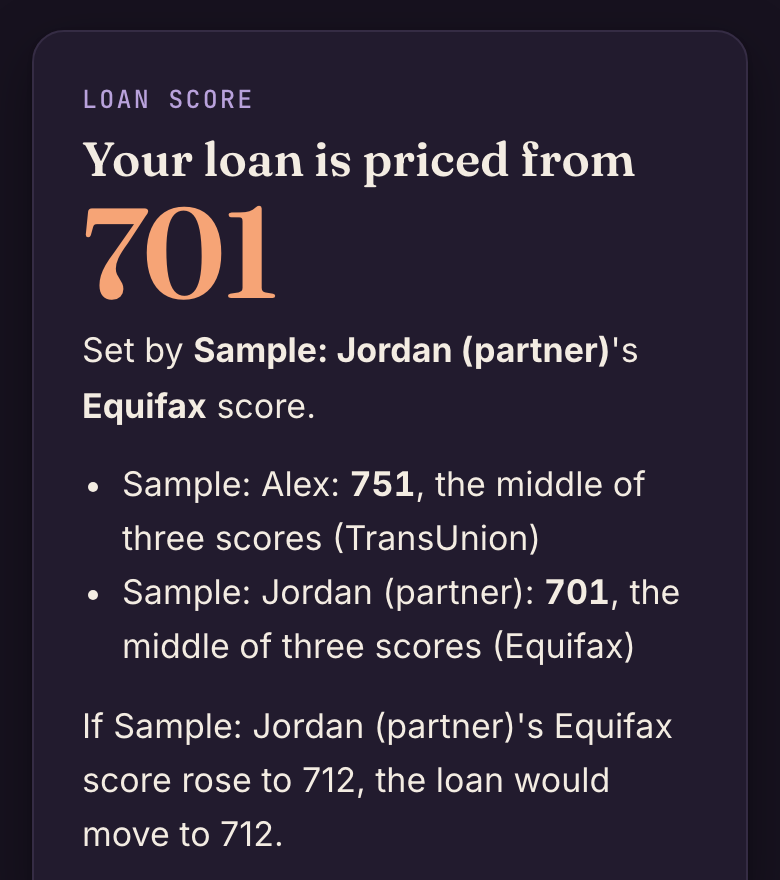
The Credit Kindred app on a phone, dark theme: the loan is priced from 701, set by the partner's Equifax score (sample data).

The household board

Everyone, every bureau, every next step, on one screen.

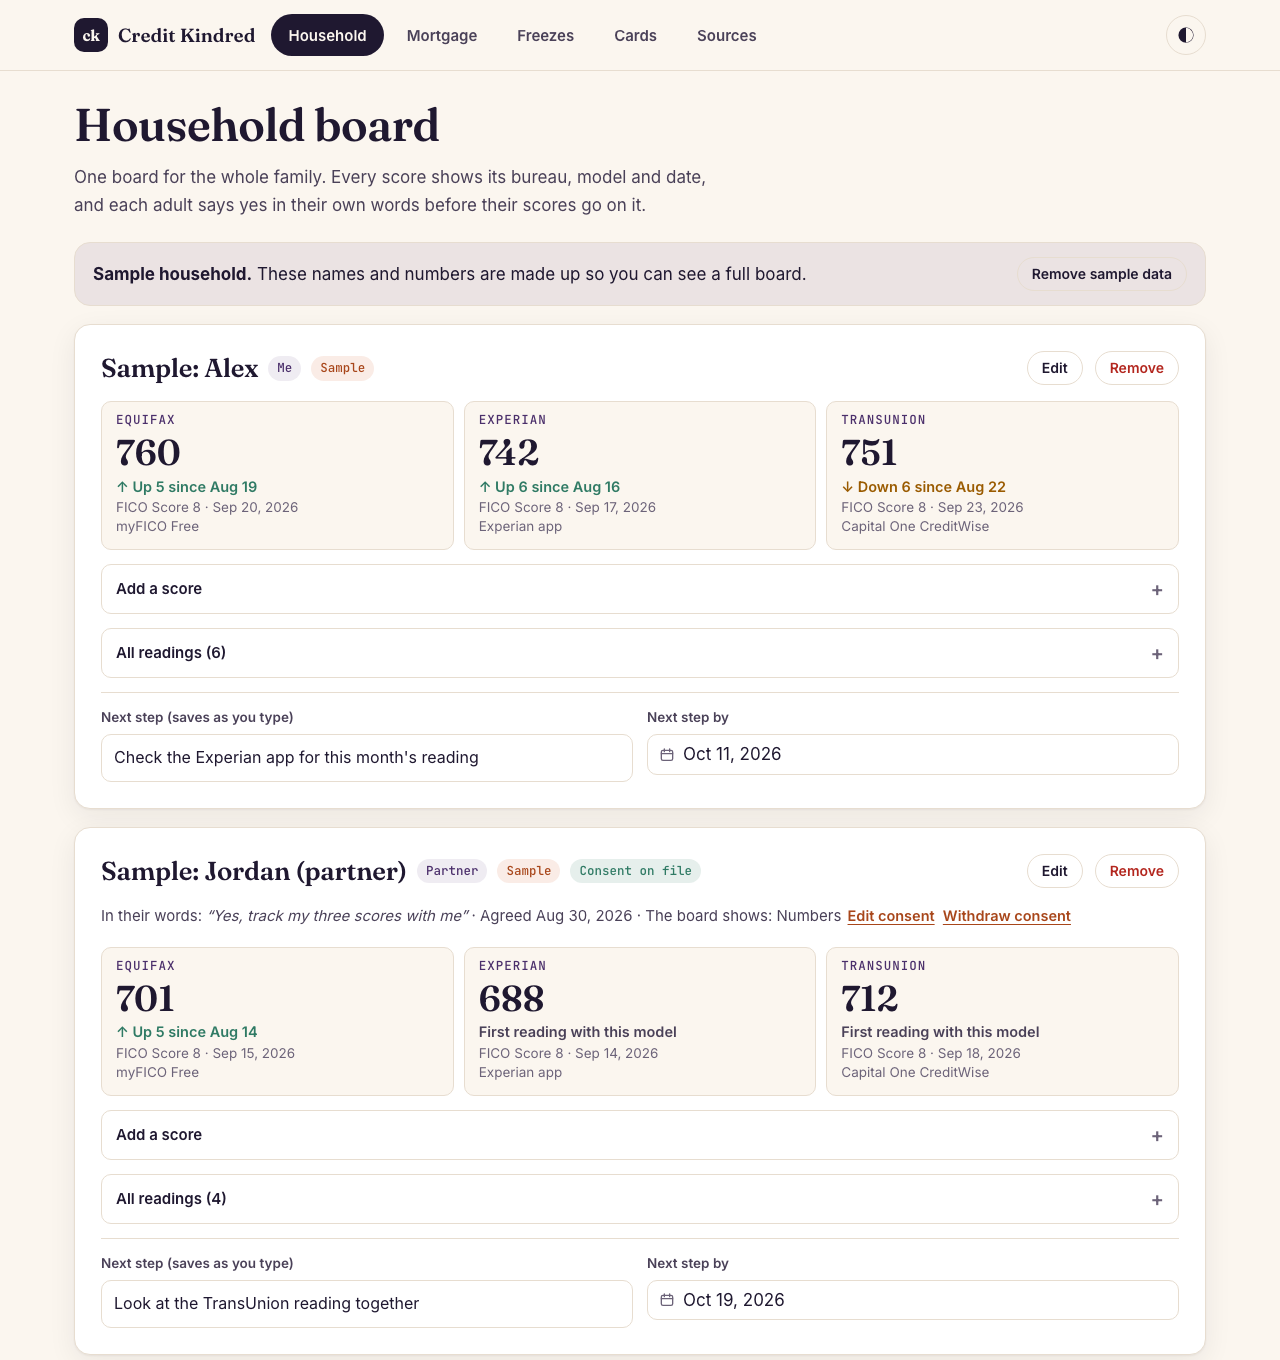
This is the real board, filled with a sample household: three labeled readings per adult, consent in each partner's own words, children tracked by their freezes, and a date on every next step.

The Credit Kindred household board with sample data: Alex's Equifax 760, Experian 742 and TransUnion 751, each labeled FICO Score 8 with a date and source; Jordan, the partner, with consent recorded in their words.

Open your board, free

Why a family board

Free credit apps are built for one person. Families are not.

Every free credit app we reviewed covers a single adult. Meanwhile the jobs that matter most sit between people: a child's freezes, a parent's fraud risk, two partners buying one home.

915,000

children in the US had their identities misused in one year, about 1 in 80.

AARP and Javelin Strategy, 2022 study
$7.7B

lost to cybercrime by Americans 60 and older in 2025, up about 60%.

AARP, on FBI data
12

freeze requests to cover a family of four at Equifax, Experian and TransUnion.

4 people × 3 bureaus
11

free credit apps reviewed. Each one shows a single person.

Credit Kindred research, September 2026

Try it now · Mortgage score for two

Buying together? Your loan is priced from the lower partner's middle score.

Lenders take each borrower's middle score across the three bureaus, then price the loan from the lowest of those. Type both partners' scores and see exactly which number sets your rate.

You
751middle
Your partner
701middle

Rule: Fannie Mae Selling Guide B3-5.1-02. Three scores use the middle one, two use the lower, one uses itself; the loan uses the lowest across borrowers. Lenders pull their own scores, often older FICO versions or VantageScore 4.0, so free scores are a close guide.

Your loan is priced from

701

Set by your partner's Equifax score.

Raise that one score to 751 and the loan moves to 751.

Save it to your board

How it works · Five people, five jobs

One board for everyone you look after.

Add the people in your household. Credit Kindred gives each one the job that fits their life, and puts a date on the next step.

[01] YOUR PARTNER

Two people, one plan, both by consent.

Your partner joins the board in their own words and chooses how they appear: full numbers, or direction only. Their three scores sit next to yours, labeled by bureau and model, so the two of you plan a home, a car or a card from the same page.

  • Consent recorded in their words, with the date
  • Numbers or direction only, their choice
  • Mortgage score for two, filled straight from the board
[02] YOUR KIDS

Freeze every child at all three bureaus, and know it stuck.

A child's freeze is free by federal law, and each bureau runs its own paperwork. Credit Kindred tracks every child at Equifax, Experian and TransUnion: requested, documents sent, confirmed. It keeps the checklist, the official links, and a note of where each freeze PIN is kept.

  • Status and dates for each bureau, per child
  • Document checklist and a printable packet
  • The year each child turns 16, on the calendar
[03] YOUR PARENTS

Look after a parent's credit the way the bureaus require.

Acting for a parent takes a power of attorney or a guardianship on file at each bureau. Credit Kindred lays out what each bureau asks for, tracks every request, and keeps your parent on the same board as everyone else, by their consent while they can give it.

  • Authority documents on one checklist
  • Freeze status at each bureau, with dates
  • A next step for the family to share
[04] YOUR CARDS

Know what every card reports, and the day it reports it.

A card reports its balance when the statement closes, not when the bill is due. Add each card's limit, balance and closing day and Credit Kindred shows what it will report, the date it closes, and the payment that brings it to the level you choose.

  • Next closing date for every card, in order
  • Utilization per card, per person and household
  • Pay-before-close amounts at 1%, 9% or 29%
[05] EVERY SCORE, LABELED

Every number carries its bureau, model and date.

A VantageScore from one bureau and a FICO Score from another are different numbers. Credit Kindred never shows one without its label, compares readings only within the same model, and shows where each free score comes from, including three free FICO Score 8 readings, one per bureau.

  • Bureau, model and date on every reading
  • Direction only within the same model
  • A map of the free sources and what each one gives

Built for the moments that matter

The days a family's credit decides something.

Credit rarely matters on an ordinary Tuesday. It matters on a handful of days, and those days usually involve more than one person. Here is what the board does on each of them.

Buying a home together

Know the number your lender will price from.

Enter both partners' three scores and see the loan's representative score: each partner's middle score, then the lower of the two. The board names the one bureau score that sets it, so the two of you know which card to pay down and which statement date to beat before the lender pulls credit.

A new baby

Freeze a newborn's credit before anyone else can use it.

Once a child has a Social Security number, a parent can place a protected-consumer freeze at each bureau for free. The freeze tracker lists the three requests, the documents each bureau asks for, and the official page for each, then holds the status until all three read confirmed.

A teenager turns 16

Keep every child's freeze on the calendar.

Federal protections for a protected-consumer freeze are written for children under 16. The board keeps the year each child turns 16 in view, so the family can confirm with each bureau how the freeze carries forward, and the child's card is ready for the day they become an adult who joins by their own consent.

A parent needs help

Act for a parent with the paperwork in order.

Acting at the bureaus for an aging parent takes a power of attorney or a guardianship on file at each one. The checklist holds the authority documents, the tracker holds each request and its date, and the whole family sees the next step on the same board.

Fraud in the family

Lock everyone down in an afternoon.

When one person's details turn up in a breach, the rest of the household is often next. The tracker shows who is frozen at which bureau and who is not, so the gaps are visible at a glance and every missing freeze has a link and a checklist beside it.

Every month

Pay before the date that counts.

Cards report balances when statements close. The statement planner lists every card in the household by its next closing date and shows the payment that brings each one to the level you choose, so the balance your family carries is the balance you meant to report.

Start this week · About 20 minutes

Three steps from scattered to organized.

Everything you need is free, and each adult pulls their own. Here is the order that gets a family onto one board fastest.

1

Pull your free reports

Each adult visits annualcreditreport.com, the site federal law set up for free reports, answers a few identity questions, and opens their report from Equifax, Experian and TransUnion. It is free every week. Note anything you do not recognize: an account, an address, an inquiry.

2

Get one score per bureau

Free FICO Score 8 readings exist for all three bureaus: Experian through the Experian app or Amex MyCredit Guide, TransUnion through Capital One CreditWise, and Equifax through myFICO Free. Record each one on the board with its date. The board keeps the labels straight so you never compare two different models.

3

Start the freezes

Open the freeze tracker, pick a child or a parent, and work through the checklist: birth certificate, Social Security card, your photo ID, proof of address and proof of authority. Send the three requests, mark each one, and come back when the confirmations arrive. Freezes are free and can be lifted any time.

The words on the page

Six terms that decide most family credit questions.

Middle score
With a score from each of the three bureaus, a mortgage lender sets the highest and lowest aside and uses the one in the middle. With two scores it uses the lower one. Couples then use the lower of the two partners' numbers.
Utilization
The share of your credit limits you are using, card by card and in total. A $900 balance on a $10,000 limit is 9%. Scoring models look at it as of the date each card reports.
Statement closing date
The day a card cuts its monthly statement, usually about three weeks before the payment is due. The balance on that day is typically the one reported to the bureaus.
Security freeze
A block at one bureau that stops new lenders from seeing your file, so no one can open credit in your name there. It is free, it does not affect your score, and you lift it with a PIN or account when you apply for something.
Protected-consumer freeze
A freeze a parent or guardian places for a child under 16, or a representative places for an adult under guardianship or power of attorney. The bureau creates a record just to freeze it, so a child's identity cannot be used to open credit.
Soft and hard inquiries
Checking your own credit, and most preapproval screening, is a soft inquiry and does not affect your score. Applying for credit usually causes a hard inquiry, which lenders can see and which can lower a score slightly for a while.

Compare

A whole household, for free.

Family credit today means a paid identity plan with a cap on adults, or a stack of free single-person apps. Here is how they line up.

Credit KindredCredit KarmaExperian FamilyEquifax Complete FamilyAura Family
PriceFreeFree$34.99 a month$29.95 a month$32 a month, billed yearly
Adults on one accountEveryone you add, by consent1225
ChildrenEveryone you addNoneUp to 10Up to 4Unlimited
Children's freezesTracked at all three bureaus, with checklistsLinks to each bureauExperian file check for a minorEquifax lock onlyPre-filled requests for all three
Mortgage score for twoYes, liveNot offeredNot offeredNot offeredNot offered

Prices and plan details as shown on each company's own pages on September 29, 2026: Credit Karma, Experian, Equifax, Aura. "Not offered" means we found no such feature on the company's product pages that day. Credit Kindred is not affiliated with any company named here.

Questions

Answered plainly.

Is it really free?

Yes. Every tool on this page is free: the household board, the mortgage score for two, the freeze tracker, the statement-close planner and the map of free score sources. There is no trial and nothing to cancel.

Can I see my partner's or my parent's credit without asking them?

No, and Credit Kindred is designed that way on purpose. Every adult's credit file belongs to them. On your board, another adult's scores appear only after you record their consent in their own words, with the date. They choose whether the board shows numbers or just the direction.

Does Credit Kindred pull my credit?

No. Each person gets their own free reports at annualcreditreport.com and their own free scores from sources like the Experian app, Amex MyCredit Guide, Capital One CreditWise and myFICO. You record what matters on the board. Credit Kindred signs in to no bureau, bank or card account.

Will using it affect anyone's score?

No. Entering a score on your board touches no credit file. Checking your own credit is also a soft inquiry and does not affect your score.

Is freezing my child's credit really free?

Yes. Federal law makes security freezes free, including for children under 16, whose freeze a parent requests as a protected-consumer freeze (15 U.S.C. 1681c-1). Each bureau has its own form and documents; the freeze tracker keeps all three straight.

Why is my free score different from the one my lender sees?

Different bureaus hold slightly different data, and different score models weigh it differently. Many free apps show a VantageScore; mortgage lenders often use older FICO versions or VantageScore 4.0. That is why Credit Kindred labels every reading with its bureau, model and date, and compares readings only within the same model.

How does the mortgage score for two work?

For each borrower, the lender takes the middle of three bureau scores (the lower of two, or the only one). The loan is then priced from the lowest of those numbers across all borrowers, per Fannie Mae's Selling Guide B3-5.1-02. Credit Kindred shows the number and the one score that sets it.

Where is my family's information kept?

Everything you enter is saved in this browser on this device. You can export the whole board as a file, import it on another device, or clear it in one step.

Is this credit repair?

No. Credit Kindred is an organizer for your family's credit: scores, freezes, cards and dates. It is not a credit repair service, a credit bureau or a lender, and it does not give legal or financial advice.

Should I freeze my own credit too, not just my kids'?

Many adults do. A freeze at each bureau stops new lenders from opening accounts in your name, costs nothing, and leaves your existing cards and score untouched. The freeze tracker works the same way for an adult as for a child: three bureaus, a status and a date for each, and a note of where each PIN is kept.

Will a freeze get in the way when we apply for a mortgage?

Only if it is still on when the lender pulls your credit. Lift the freeze at each bureau shortly before you apply, either for a set window or until you refreeze, and mark it Thawed on the board so the family can see who is open and who is protected. Once the loan is done, refreeze and mark it again.

What if a report shows an account nobody in the family opened?

Treat it as possible identity theft and act the same day. Freeze that person's credit at all three bureaus, then use the Federal Trade Commission's IdentityTheft.gov, which builds a personal recovery plan and the reports you need. Contact the bureau showing the account and the company named on it. Mark the steps on the board so everyone in the family knows where things stand.

Does it work on my phone?

Yes. Credit Kindred runs in any modern browser on a phone, tablet or computer.
Start in two minutes

Put your whole family on one board.

Add yourself, your partner and your kids. Record each adult's consent, start the three freezes, and see what every card reports next.

Open your household board